
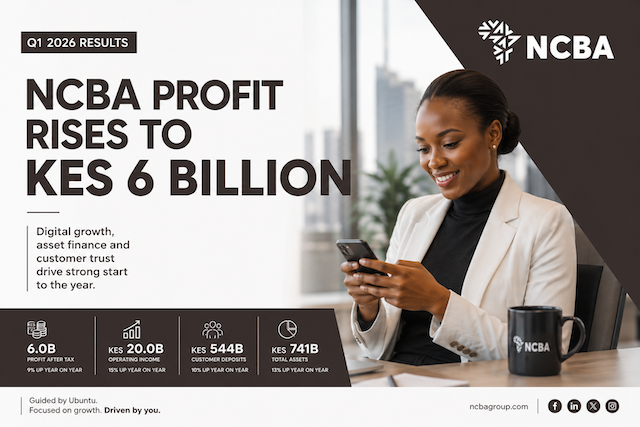
NCBA Digital Lending Growth helps lift quarterly profit as deposits, asset finance and regional business expand steadily.
NCBA Group is starting 2026 on a profitable note, posting a KES 6 billion profit after tax for the first quarter as digital lending, asset finance and customer deposits continue to grow across its business. The lender’s latest results also show a sharp rise in provisions for bad loans, reflecting the cautious mood currently shaping Kenya’s banking sector.
The results place the bank among the lenders continuing to post growth despite pressure from rising loan defaults, cautious borrowing, and an unpredictable economic climate across the region. NCBA’s operating income stands at KES 20 billion, up 15 per cent year-on-year, while customer deposits have grown to KES 544 billion. Total assets have also climbed to KES 741 billion. The numbers reflect a banking sector that is increasingly leaning on digital transactions, asset finance, and SME lending to keep revenue moving.
One of the clearest signals in NCBA’s latest results is how deeply digital banking has become part of everyday financial activity. The bank says 98 per cent of all transactions are currently happening through digital channels. Digital loan disbursements for the quarter have reached KES 391 billion, representing a 27 per cent increase compared to Q1 2025.
NCBA is also pushing further into SME lending through its newly launched NCBA BOOSTA product, which gives businesses access to loans of up to KES 35 million through digital channels. At the same time, the bank’s asset finance business continues to hold a major share of the market. NCBA says it currently commands 32 per cent of Kenya’s asset finance market, while its vehicle marketplace platform CarDuka has attracted close to seven million users.
Speaking during the release of the results, NCBA Group Managing Director John Gachora says the lender is focused on strengthening its core operations while scaling areas showing faster growth.
“As we present our financial results for the first quarter of 2026, I am pleased to report that the Group has delivered a strong start to our new strategy,” he says.
He adds that the growth in operating income reflects “sustained business growth, improved revenue diversification and continued resilience across core operating segments.”
Even with the improved profits, NCBA is taking a cautious approach toward lending risks. The bank’s provision for credit losses has risen by 56 per cent to KES 2.5 billion. The increase points to continued pressure on businesses and households dealing with higher costs, expensive credit and slower cash flow in several sectors of the economy.
Gachora says the higher impairment charges come from “a prudent approach to credit risk assessment given the heightened volatile operating environment.”
Operating expenses have also risen by 9 per cent to KES 9.7 billion. Still, the group’s capital adequacy ratio remains at 21.8 per cent, comfortably above the regulatory minimum of 14.5 per cent.
NCBA Digital Lending Growth – Regional Subsidiaries Continue Contributing to Growth
While Kenya remains NCBA’s largest market, the group’s regional subsidiaries are continuing to contribute to overall earnings. Operations in Uganda, Tanzania and Rwanda are posting a combined profit before tax of KES 707 million.
Meanwhile, NCBA Bank Kenya remains the group’s biggest profitability driver, recording a 20 per cent increase in profit before tax to KES 6.5 billion. The bank’s non-banking subsidiaries are also adding to the numbers. NCBA Investment Bank, insurance, leasing and bancassurance businesses are collectively reporting KES 641 million in profit before tax.
Wealth management is becoming a bigger part of the business as well. Assets under management at NCBA Investment Bank have now crossed KES 101.5 billion, while the number of wealth customers has surpassed 60,000. Insurance operations are also growing steadily, with NCBA Insurance and BancAssurance recording combined gross written premiums of KES 5 billion.
NCBA is also putting money into technology infrastructure as competition among banks increasingly shifts toward digital service quality and reliability. The lender says service uptime currently stands at 99.74 per cent following investments in cybersecurity systems, customer relationship management tools and AI-powered onboarding and credit systems.
Its upgraded corporate banking platform, NCBA ConnectPlus, is currently supporting KES 181 billion in lending and KES 211 billion in deposits within the corporate segment. The bank also says customer satisfaction scores on digital channels continue to improve.
Beyond traditional banking, NCBA is continuing to place money into green financing and community programmes. The group recently acted as lead arranger for the Kenya Mortgage Refinance Company green bond that raised KES 3 billion. It also served as trustee and receiving bank for the KES 4.8 billion Two Rivers International Finance and Innovation Centre green REIT.
NCBA says it has also disbursed KES 190 million in green financing during the quarter.
Looking ahead, the bank says its proposed transaction with Nedbank Group remains on course, while management continues monitoring tensions in the Middle East and their possible effect on inflation, liquidity and financial markets.
Never miss a story 💜
Breaking news, real stories and money tips for Kenyan women, as they happen.

