
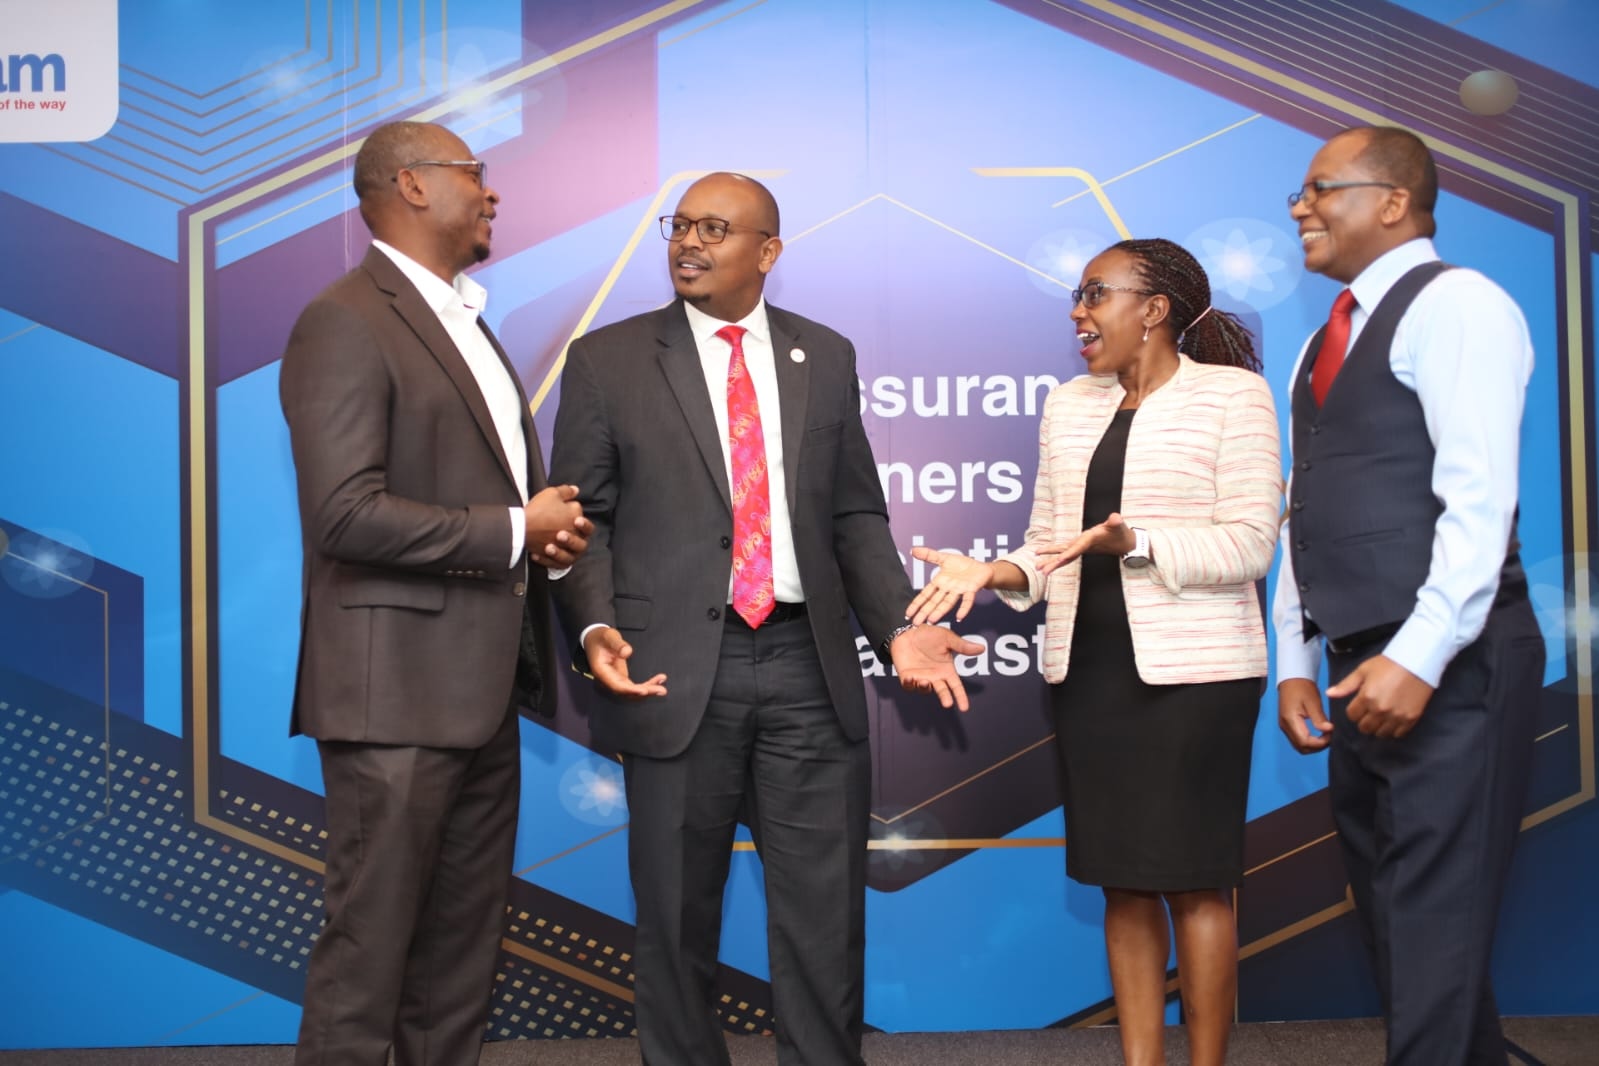
Britam Marine Insurance Kenya promotes cargo protection, business resilience, trade confidence, and blue economy growth amid evolving risks.
As Kenya strengthens its position as a regional trade and logistics hub, Britam is calling for greater adoption of marine insurance solutions to help businesses navigate emerging risks and seize opportunities within the country’s growing blue economy.
Kenya’s maritime sector continues to play a strategic role in economic growth, with the Port of Mombasa serving as a key gateway for East and Central Africa. However, businesses involved in import, export, transportation, and logistics face geopolitical tensions, cyber threats, climate-related disruptions, piracy, and evolving trade regulations that are reshaping the risk landscape for businesses that rely on cross-border goods movement.
Industry data shows that Kenya’s Marine Cargo Insurance sector generated KSh 2.94 billion in Insurance Service Revenue (ISR) in 2025, delivered by 32 active underwriting companies. While this reflects a resilient market closely aligned with global trade flows and regional cargo movements, it also highlights a significant growth opportunity for the insurance sector.
Despite this performance, marine insurance penetration remains relatively low compared to the scale of Kenya’s import economy, which exceeds KSh 2.7 trillion annually.
Speaking during the Britam Marine Insurance Masterclass in Nairobi, industry experts highlighted a substantial protection gap within the country’s import-driven trade ecosystem and underscored the need for greater awareness and uptake of cargo and trade-related insurance solutions.
“Today’s businesses face a complex risk environment that spans global supply chains, geopolitical uncertainty, digital vulnerabilities, and climate-related disruptions,” said James Mbithi, Chief Executive Officer, Britam General Insurance. “Marine insurance is a critical business continuity tool that enables enterprises to move goods across borders with greater certainty and resilience.”
The movement of cargo remains exposed to a wide range of risks, including vessel collisions, fires, explosions, piracy, adverse weather conditions, cargo damage, and human error during loading, storage, and transportation. This increases the need for integrated risk management solutions that can keep pace with evolving trade patterns.
The Masterclass also examined how technological advancements are transforming marine insurance by enabling customers to purchase marine insurance, generate cargo certificates, and track shipments more efficiently. However, experts noted that digital transformation could also introduce new cybersecurity risks, requiring businesses to adopt more comprehensive risk mitigation measures.
“A single disruption can have significant financial consequences as today’s businesses operate in an interconnected environment,” said Joe Kamomoe, Chief Executive Officer of MarinaiR Surveyors and Adjusters. “Strong risk mitigation measures, supported by robust marine insurance coverage, is key for businesses seeking to protect assets and maintain operational continuity.”
The event also recognised the role of bancassurance partnerships in expanding access to specialised insurance solutions for businesses and individuals across Kenya.
As Kenya accelerates investments in trade infrastructure, logistics, shipping, and blue economy initiatives, Britam reaffirmed its commitment to delivering innovative insurance solutions that help businesses manage risk, protect value, and pursue growth opportunities with confidence.
The forum brought together banking partners, insurance professionals, risk experts, and marine survey specialists to discuss emerging trends in marine insurance and the role of risk protection in supporting business continuity.
Never miss a story 💜
Breaking news, real stories and money tips for Kenyan women, as they happen.

