
Absa Digital Payments Future will rely on wearables, smartphones, AI security, and invisible banking experiences for consumers.
For years, bank cards in Kenya were mainly associated with ATMs and cash withdrawals. Today, payments are increasingly happening through smartphones, apps, digital wallets, and even wearable devices.
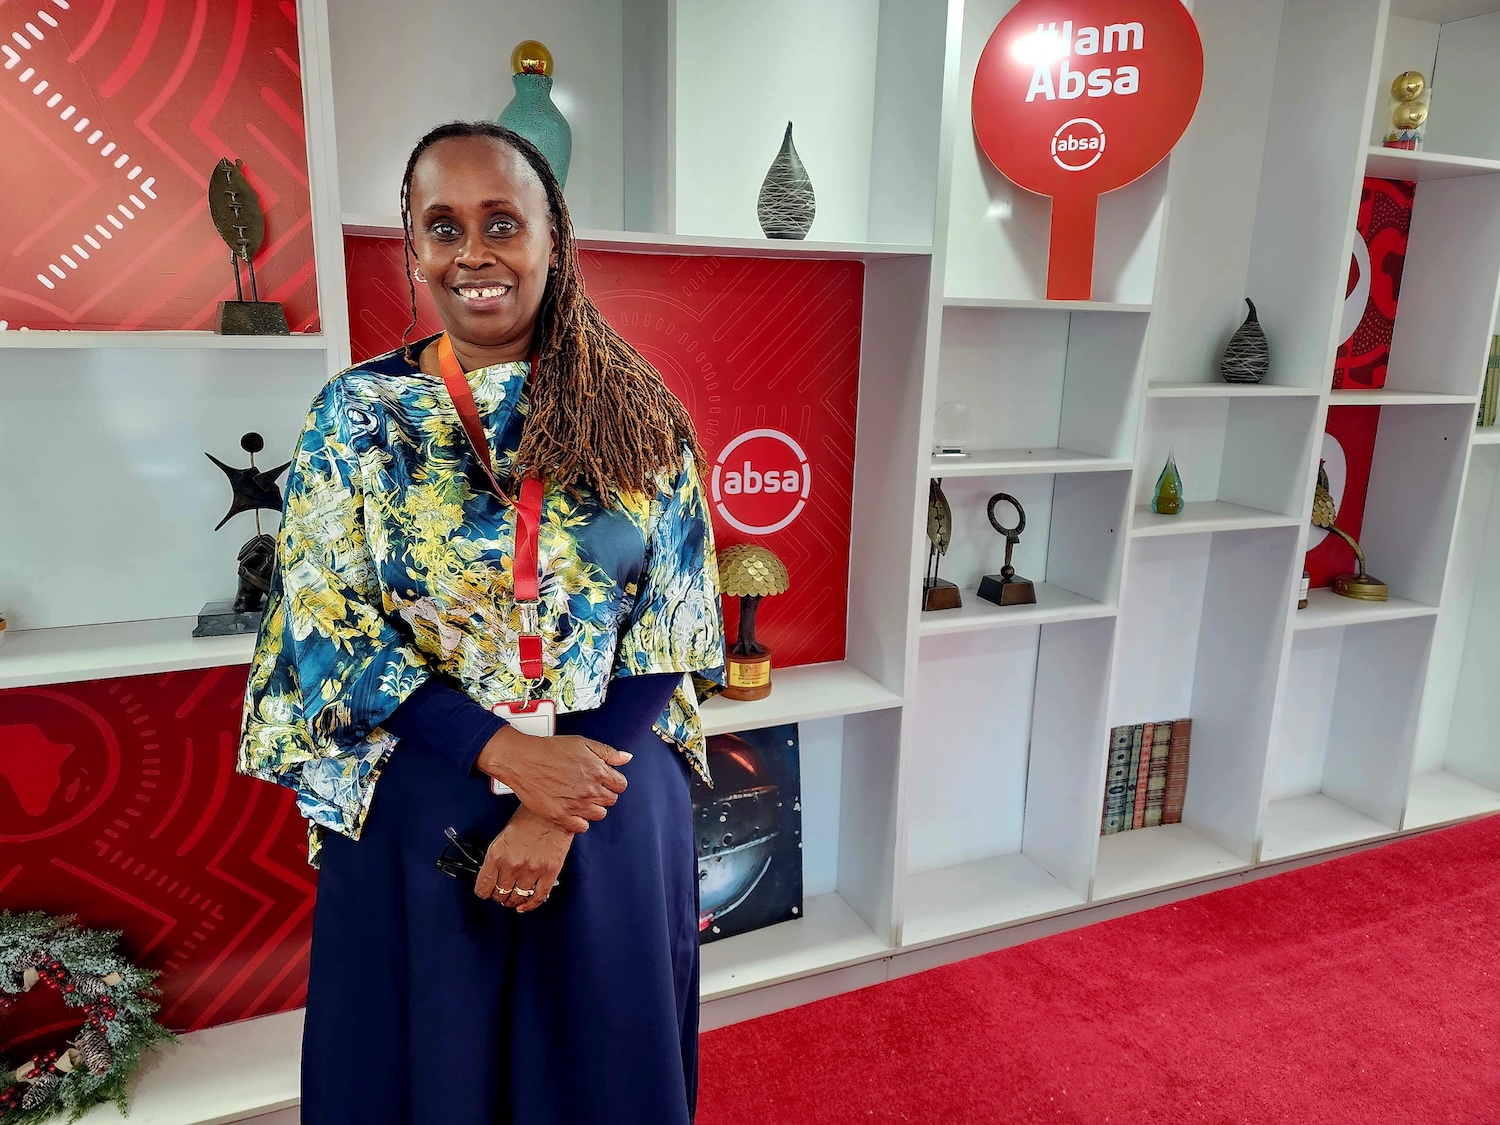
As Head of Card Payments at Absa Kenya, Linda Kimani has spent years watching that shift happen in real time. In this interview with FemmeHub, she speaks about how digital lifestyles are changing banking, why wearable payments are growing, and what the future of virtual payments could look like for Kenyan consumers.
Please introduce yourself and tell us what you do at Absa.
My name is Linda Kimani and I head the card payments business at Absa Kenya. I’ve been with the bank for 18 years, although across different roles over that period. I previously worked in transactional banking and debt management, but most of my career has been within the payments space, which is where I’ve spent a significant amount of time.
It’s a very interesting industry because payments continue evolving every day. You’re constantly seeing innovation and changing customer behaviour at the same time. Payments are also closely tied to everyday lifestyle because every single day, people are making some form of payment, whether it’s for travel, shopping, entertainment, school fees, or business. It’s one of those spaces where you directly see how technology changes how people live.
Cards have changed a lot over the years. What do you think has been the biggest shift in how Kenyans use cards today compared to a few years ago?
When cards first entered the market, most people mainly associated them with ATM access. In fact, for a very long time, many customers simply referred to them as ATM cards because that was the main relationship people had with them. You withdrew cash from the ATM or occasionally used the card at a point-of-sale terminal.
Over time, that perception has changed significantly. Today, cards have evolved from being simple payment tools into lifestyle enablers. They now sit at the centre of how people move through their daily lives. If you look at the last five years in particular, that transformation has accelerated very quickly as payments shifted toward digital channels.
Customers increasingly want payment options integrated into the environments they already use every day. People spend most of their time on smartphones now, whether for work, entertainment, shopping, communication, or social interaction. Naturally, payments have had to follow that behaviour. Banks are no longer building products around physical banking habits alone. We now have to build around digital lifestyles.
That is why you are seeing cards being integrated into mobile wallets, smartphones, wearable devices, and other digital ecosystems. A customer can now complete transactions without necessarily carrying a physical card. They can tap their phone, pay through a wearable, shop online, or integrate their card into other platforms and payment environments.
The younger generation especially is very comfortable operating digitally first. Many of them don’t have the same attachment to physical banking tools that older generations had. Their lives already happen through digital devices, so naturally they expect payments to happen there too.
Read also – Absa Bank and Visa Unveil Kenya’s First Metal Infinite Card
Absa’s Infinite Card combines payments, travel, lifestyle experiences and digital features. What informed that direction?
The Infinite Card was built around a customer segment that is highly exposed, digitally aware, and very lifestyle-oriented. These customers travel often, value convenience, appreciate premium experiences, and want flexibility in how they transact.
We wanted the card itself to immediately feel different from traditional products in the market. That is why we went with a premium metallic design and a vertical card format, which is still relatively unique in this region. The physical appearance matters because this customer appreciates detail and experience.
But beyond the aesthetics, the real thinking was around how affluent customers actually live today. They want payment experiences that fit naturally into their routines without friction. They are among the biggest users of smartphones, digital applications, and connected devices, so we built the proposition around that reality.
For example, we embedded digital payment capabilities directly into the proposition so customers can complete transactions through their phones or wearable devices instead of depending entirely on physical cards. We also focused heavily on travel and lifestyle benefits because these customers spend significantly in those categories.
At the same time, affluent customers are very conscious about value. People often assume high-spending customers are not price sensitive, but they actually pay close attention to the value they receive from every product they use. That is why rewards are an important part of the proposition. Customers want to feel that their spending translates into meaningful benefits and experiences.
We’ve also started thinking more broadly about how premium products can eventually tie into areas like sustainability and customer impact. Even the card itself reflects that thinking through the use of metal materials and the overall design approach.
The reception has honestly been very encouraging. We’ve seen strong interest not only from existing customers but also from people who bank elsewhere and are attracted by the proposition and the experience around the product.
Who qualifies for the Infinite Card?
There is sometimes a perception that premium cards are only for a very small category of ultra-wealthy individuals, but we look at several factors beyond traditional wealth definitions.
Of course, high-net-worth customers naturally fit into that segment, but we also consider spending behaviour, travel patterns, lifestyle preferences, and overall customer profile. We have CEOs, senior executives, entrepreneurs, company directors, and professionals who use the product because it aligns with how they live and spend.
We also have retirees with significant asset wealth who qualify. Some customers may not necessarily fall into stereotypical luxury categories, but they have spending habits and lifestyle needs that make the proposition relevant to them.
The idea was not to create something that feels inaccessible, but rather something that fits customers who value convenience, experiences, and premium digital payment capabilities.
Security remains one of the biggest concerns around digital payments. How is Absa helping customers feel safer as banking becomes increasingly digital?
Security is extremely important because as payments become more digital, fraud methods also become more sophisticated. As a bank, we invest heavily in fraud monitoring systems, authentication layers, and customer protection measures because trust sits at the centre of digital banking.
One of the major shifts we introduced over the last few years was expanding contactless payment capabilities. Customers can now tap cards, phones, or wearables to complete transactions quickly and conveniently. But behind that convenience are several layers of security controls working continuously in the background.
One area we’ve invested in heavily is tokenisation. What tokenisation does is protect the customer’s actual card details during transactions. Instead of exposing the real card number during payment processing, the system generates a secure digital token for that transaction. That means customers can transact digitally without leaving sensitive card information exposed across different platforms.
We have also strengthened security around online payments through additional authentication layers such as one-time passwords and 3D security protocols. Fraud has increasingly shifted toward cyber channels, especially e-commerce environments, so banks have had to adapt quickly to that reality.
The interesting thing about fraud management is that the fraudsters are also constantly evolving. They are becoming more advanced and increasingly sophisticated in how they operate, including the use of AI and digital tools. That means fraud prevention systems also have to keep evolving through real-time monitoring, behavioural analytics, and data-driven fraud detection.
The balance is always finding ways to make payments feel seamless for customers while still protecting them behind the scenes.
The new card also leans heavily into wearable payments and digital-first experiences. What informed that strategy?
A lot of it comes directly from observing how customers interact with technology today. People increasingly want convenience and speed. They don’t want payment experiences that feel complicated or disconnected from their lifestyle.
Wearables are a good example of that shift because they combine multiple parts of a customer’s daily life into one experience. Someone may already use a wearable device for fitness, health tracking, travel, or communication, so integrating payments into that environment becomes very natural.
We partnered with Garmin because many of our target customers are active and wellness-oriented. They play golf, travel frequently, walk regularly, or engage in fitness activities, so the wearable already fits naturally into their routines. Adding payment functionality simply removes another layer of friction from the customer experience.
The reactions have been very interesting because many people still find wearable payments surprising the first time they see them happen. You can go to a merchant location and the cashier expects you to remove a physical card, then suddenly you tap a watch and complete the transaction. There is usually a genuine moment of surprise.
We’ve seen adoption continue growing over the last few months because once customers experience the convenience, it becomes easy to integrate into daily life. Even small everyday transactions become faster and easier.
Over time, we expect this area to continue evolving. Different customers will prefer different forms of wearables, including watches, rings, wristbands, and other connected devices. Payments are gradually becoming embedded into the devices people already use daily.
You mentioned younger consumers earlier. How are they changing the payments space?
Younger consumers are extremely digital and very comfortable with technology. A lot of their lives already exist through smartphones and digital platforms, so naturally they expect financial services to work the same way.
Many younger customers are less attached to physical banking tools and traditional processes. They appreciate speed, convenience, and flexibility. If a payment process feels slow or complicated, they move away from it very quickly.
You can also see how digital platforms have changed entire industries over the last few years. The creator economy is a very good example. Today, many young people are earning income through content creation, online businesses, digital services, and social media platforms. That ecosystem barely existed at its current scale a few years ago.
Banks have to pay attention to those shifts because the next generation of customers interacts with money differently. Their expectations around payments, access, convenience, and digital integration are shaping the future of financial services.
Buy Now Pay Later has become increasingly popular globally. How is Absa approaching it?
Buy Now Pay Later is essentially a modern evolution of installment-based financing. The concept itself is not entirely new because people have always needed ways to spread payments over time. What has changed is how seamlessly technology now allows that process to happen.
What we’ve done is integrate Buy Now Pay Later directly into the customer payment journey. A customer can complete a transaction and then immediately structure it into installments digitally through the app.
This works particularly well for lifestyle spending, appliances, travel, school fees, and even unexpected expenses that may arise suddenly. Customers get flexibility around cash flow management without necessarily delaying important purchases or payments.
School fees are a good example because they often create pressure for households at certain periods during the year. Instead of schools carrying the burden of installment arrangements directly with parents, the bank can structure that repayment through the card platform while the school receives payment immediately.
Customers also appreciate the convenience because the process is fully digitised. They can view eligible transactions within the app and decide which purchases they want to convert into installment plans. It gives customers additional breathing room financially while keeping the process simple and accessible.
We expect this area to continue growing because customers increasingly want flexible financial solutions that fit around real-life spending patterns and income cycles.
What are affluent customers asking for today compared to five years ago?
They are far more digital and far more informed today. They expect seamless experiences and they appreciate innovation that genuinely improves convenience.
They also value exclusivity and personalised experiences. That could mean travel partnerships, airport lounge access, premium dining experiences, hotel offers, or tailored rewards connected to their lifestyle.
One interesting shift is that many affluent customers rarely want to interact with cash anymore. They prefer payment systems that feel smooth, integrated, and almost invisible within their daily routines.
At the same time, they remain highly conscious about value. Even high-spending customers want to know they are getting meaningful benefits from the products they use. That is why partnerships and rewards continue becoming more important within premium banking.
Customers today are also very exposed globally. They travel, they interact with international products, and they compare experiences across markets. That pushes banks to continuously innovate and improve what they offer locally.
Absa Digital Payments Future – From your perspective, what will banking and virtual payments look like over the next five years?
The movement toward digital-first payments will continue accelerating very quickly. Physical cards will still exist, but they will become less central as more payments move onto smartphones, wearables, wallets, and integrated digital ecosystems.
Customers increasingly expect payments to happen naturally within whatever environment they are already using. That means banking will continue becoming more embedded into everyday digital experiences rather than existing as a completely separate activity.
We are also seeing greater integration between different payment ecosystems. Customers want to move money seamlessly between cards, wallets, digital platforms, and payment networks without friction. That interoperability will continue expanding.
AI will also play a much bigger role across banking, especially in fraud prevention, personalisation, and customer experience. Financial institutions are increasingly using data and behavioural insights to improve how they protect customers and deliver services.
Ultimately, the future of payments is moving toward convenience, speed, flexibility, and invisible banking experiences where customers transact naturally without thinking too much about the technology behind it.
Never miss a story 💜
Breaking news, real stories and money tips for Kenyan women, as they happen.

