
Kenyans have little trouble opening a financial account. Keeping money in it long enough to reach a goal is the harder part. Old Mutual Life Assurance Kenya (OMLAK) has responded by revamping its life and savings solutions, with changes aimed at strengthening long-term savings, education planning and financial security for households.
The timing reflects a gap that the data makes plain. The 2024 FinAccess Household Survey, conducted by the Central Bank of Kenya with the Kenya National Bureau of Statistics (KNBS) and FSD Kenya, found that formal financial access rose to 84.8% in 2024, up from 83.7% in 2021. Access, in other words, is widespread and still growing.
Saving consistently is another matter. Old Mutual’s 2025 Financial Wellness Monitor found that 91% of working Kenyans surveyed have a savings goal, yet 40% said they dip into their savings to cover everyday expenses. People want to build a future, but the pressures of the present keep pulling money back out.
That tension points to a need for structured savings solutions that keep households focused on defined goals such as education, home ownership and family security.
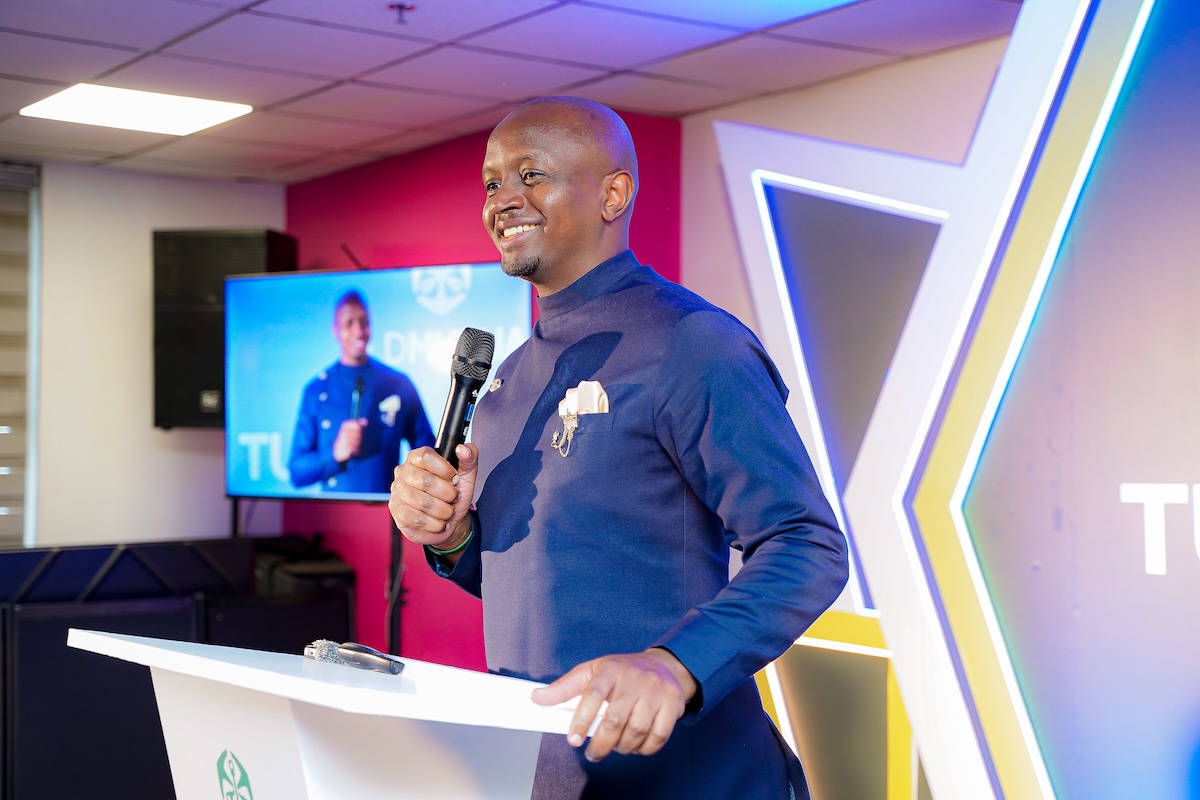
OMLAK Managing Director Martin Karenju said the findings call for products that speak to both sides of the problem. “Kenyans clearly want to save and build a better financial future, but they are doing so while managing significant pressures today,” he said. “Our responsibility is to provide solutions that help customers balance today’s needs with tomorrow’s ambitions.”
The upgrades build on Old Mutual’s existing propositions. Selected products now offer investment horizons of up to 20 years, giving savers more room to plan over the long term. Charges and surrender terms have been revised in the customer’s favour, guaranteed maturity values are higher, and benefits that support long-term education planning have been adjusted.
Behind the product changes sits a shift in how the company approaches customers. Old Mutual Group CEO Arthur Oginga said the aim is to understand the goal a customer is chasing, rather than treating each need as a separate product conversation.
“A customer does not necessarily wake up thinking about an insurance or savings product,” Oginga said. “They are thinking about paying for their child’s education, buying a home, protecting their family or having enough money when they retire. We need to begin with that goal and then help them identify the solution that can get them there.”
It is a subtle but important reframing. Instead of asking a customer which policy they want, the conversation starts with what they hope to achieve and works backward to the right solution.
The approach forms part of Old Mutual’s wider strategy to support personal growth and financial security, with solutions designed to stay relevant as customers move through different stages of life. For households balancing school fees, rent and rising costs, that flexibility may matter as much as any single feature.
If the revamped offerings work as intended, they could help close the distance between saving intentions and saving outcomes, turning good financial access into goals that are actually met.
Never miss a story 💜
Breaking news, real stories and money tips for Kenyan women, as they happen.

