
Liberty Kenya Holdings closed 2025 with a capital adequacy ratio of 2.6 times, a buffer GCR Ratings describes as sizeable against the risks the Group carries. It is one reason the agency has kept an AA+(KE) national scale financial strength rating on both of the Group’s insurance subsidiaries, Liberty Life Assurance Kenya Limited and The Heritage Insurance Company Kenya Limited, each with a Stable Outlook.
GCR points to strong risk-adjusted capitalisation, healthy liquidity and a portfolio spread across life and general insurance. It also gives weight to the Group’s relationship with Liberty Holdings Limited of South Africa, citing brand alignment, strategic importance and a track record of performance. Liquidity coverage stood at 2.2 times, up from 2.0 times in 2024, helped by growth in liquid assets and continued operational cash generation.
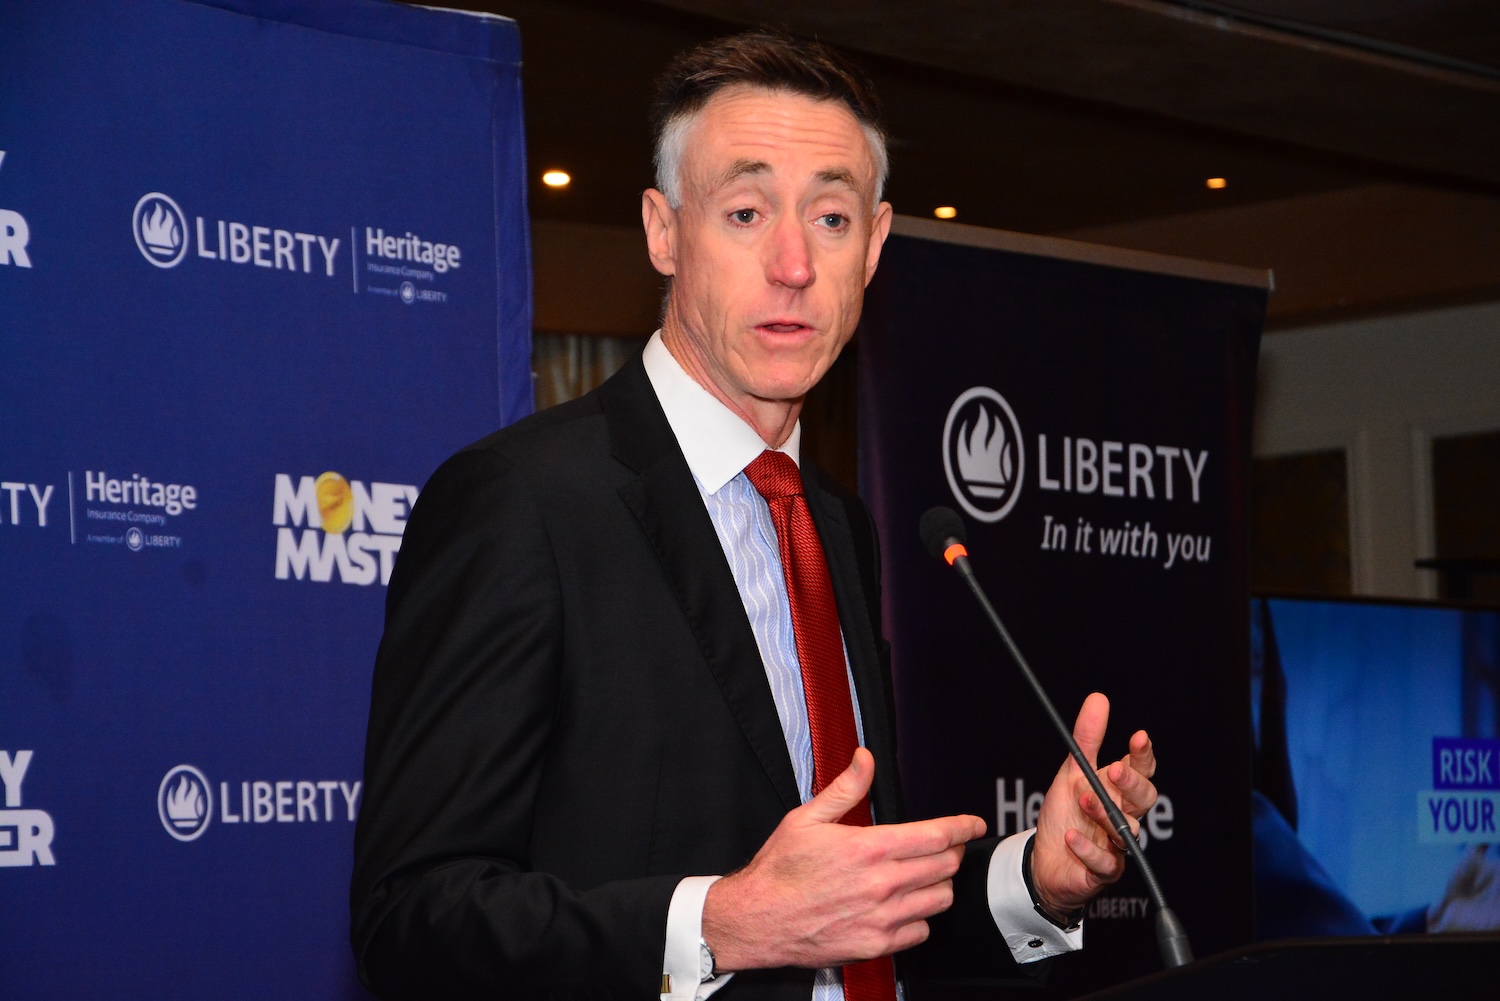
Revenue backs up the picture. Combined insurance revenue rose to KES 11.9 billion in 2025 from KES 10.9 billion the year before. Group Chief Executive Officer Kieran Godden called the affirmation “an important recognition of the financial resilience we continue to build across Liberty Kenya Holdings and our insurance businesses.” He added that financial strength “must translate into confidence for our customers, partners and other stakeholders, who rely on us to provide protection and long-term financial security.”
Liberty Life is the smaller of the two by revenue but carries the larger share of the balance sheet. Its insurance revenue grew 17.3% to KES 3.2 billion from KES 2.7 billion, led by group life and group credit insurance alongside new business growth. Its statutory capital adequacy ratio improved to 244% from 213%, following a KES 600 million capital injection from the Group through a subordinated loan. As a core operating entity, it contributed 69.9% of the Group’s assets in 2025.
Heritage Insurance is the bigger earner. Its insurance revenue grew 5.6% to KES 8.7 billion from KES 8.2 billion, supported by its medical business, and it accounted for 72.8% of the Group’s insurance revenue. Its statutory capital adequacy ratio strengthened to 466% from 451%. GCR noted that Heritage’s rating draws support from the wider Group’s capitalisation and liquidity.
The earnings line is where the year was harder. GCR noted that elevated claims and lower investment income weighed on earnings across the insurance portfolio in 2025, and it singled out claims experience in medical insurance at Heritage. The Group’s insurance service result fell to KES 478 million from KES 1.1 billion in 2024. Both insurers kept their ratings despite the pressure on earnings.
That tension sits behind the Stable Outlook. GCR expects capitalisation and liquidity to stay strong over the next 12 to 18 months, projecting a capital adequacy ratio above 2.5 times and liquidity coverage above 1.7 times. For Liberty Kenya Holdings, the ratings are independent recognition of the foundations under its insurance businesses, and a reminder that disciplined risk management and prudent capital allocation have to keep pace with growth in both life and general insurance.
Never miss a story 💜
Breaking news, real stories and money tips for Kenyan women, as they happen.

